Parts A and B built the complete delta, vega and curvature aggregation formulas part of sensitivity based method (SBM) — but both of those articles simply took a sensitivity, sk, as a given input. This part goes back to Step 1 of that process: how a bank actually calculates a sensitivity in the first place, for each of the seven risk classes, and the specific modelling choices that govern vega sensitivities in particular.
The General Rules Before the Formulas
A handful of ground rules apply across every risk class before we get to the individual formulas. Sensitivities for each risk class must be expressed in the bank’s own reporting currency. For each risk factor, a sensitivity is calculated as the change in the market value of the instrument resulting from a specified shift applied to that risk factor, while every other relevant risk factor is held at its current level — a standard ceteris paribus shock, one risk factor moved at a time.
Two further rules govern where the underlying prices and models come from. First, every delta and vega sensitivity, and every curvature scenario, must be based on instrument prices or pricing models that the bank’s own independent risk control unit uses to report market risks or actual profits and losses to senior management — not some separate, regulatory-only valuation model built purely for capital purposes.
| Connecting This to Article 4B’s P&L Definitions This is the same independent risk control unit, and the same Product Control function, that we met in Article 4B’s definitions of Actual P&L, Hypothetical P&L and Risk-Theoretical P&L. The standard is deliberately anchoring regulatory sensitivity calculations to the bank’s genuine internal risk reporting infrastructure, rather than allowing a parallel, purpose-built valuation system that might understate risk for capital purposes while the bank manages its actual risk differently day to day. |
The second rule states the underlying philosophy directly: a key assumption of the Standardised Approach is that a bank’s pricing models — the same ones used in actual profit and loss reporting — provide an appropriate basis for determining regulatory capital requirements across all market risks. To keep that assumption sound, banks must at minimum establish a framework for prudent valuation practices, incorporating the requirements of paragraphs 718(c) to 718(cxii) of the Basel II standard.
Sourced from MAR21.15–MAR21.18.
The Six Delta Sensitivity Formulas
Every delta sensitivity formula follows the same basic pattern: shift the relevant risk factor by a small, prescribed amount, recalculate the instrument’s market value, and divide the change in value by the size of the shift. What differs across risk classes is what gets shifted, and by how much.
1. Delta GIRR — PV01
The GIRR sensitivity is defined as the PV01: shift the risk-free interest rate rt at tenor t, for a given currency, by 1 basis point (0.0001 in absolute terms), and divide the resulting change in the instrument’s market value by 0.0001.
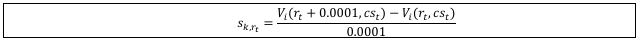
2. Delta CSR — CS01 (Non-Securitisation, Securitisation Non-CTP, and CTP)
All three credit spread risk sub-classes share the same sensitivity definition, the CS01: shift the credit spread cst at tenor t by 1 basis point, and divide the resulting change in market value by 0.0001.
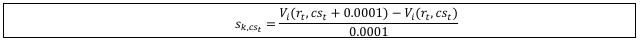
3. Delta Equity Spot
Shift the equity spot price by 1 percentage point (0.01 in relative terms), and divide the resulting change in market value by 0.01.

4. Delta Equity Repo Rates
Apply a parallel shift to the equity repo rate term structure of 1 basis point, and divide the resulting change in market value by 0.0001.
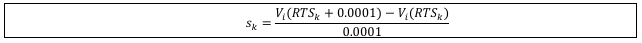
5. Delta Commodity
Shift the commodity spot price by 1 percentage point, and divide the resulting change in market value by 0.01.
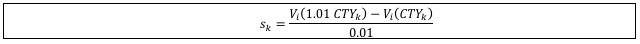
6. Delta FX
Shift the exchange rate by 1 percentage point, and divide the resulting change in market value by 0.01. The FX spot rate is the current market price of one unit of another currency, expressed in units of the bank’s reporting or base currency.

| Risk Class | Shift Size | Shift Type |
| GIRR (PV01) | 1 basis point (0.0001) | Absolute — applied to the risk-free rate at tenor t |
| CSR — all three sub-classes (CS01) | 1 basis point (0.0001) | Absolute — applied to the credit spread at tenor t |
| Equity spot | 1 percentage point (0.01) | Relative — applied to the equity spot price |
| Equity repo rates | 1 basis point (0.0001) | Absolute — parallel shift to the repo term structure |
| Commodity | 1 percentage point (0.01) | Relative — applied to the commodity spot price |
| FX | 1 percentage point (0.01) | Relative — applied to the exchange rate |
Sourced from MAR21.19–MAR21.24, including all sub-points and formulas, in full.
How Vega Sensitivities Are Measured
Vega sensitivity works differently from the six delta formulas above. The option-level vega risk sensitivity to a given risk factor is measured by multiplying the option’s vega by its implied volatility.
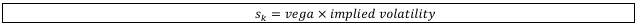
Both the vega figure and the implied volatility used in this calculation must be sourced from the pricing models used by the bank’s independent risk control unit — the same anchoring principle that applies to delta sensitivities. A footnote adds one further requirement: the implied volatility of the option must be mapped to one or more maturity tenors, as specified in the vega risk factor definitions covered in each risk class’s own article.
Sourced from MAR21.25, including its footnote.
Three Special Cases
| Case | Treatment |
| Options with no maturity | Assigned to the longest prescribed maturity tenor, and also assigned to the Residual Risk Add-On. |
| Options with no strike/barrier, or multiple strikes/barriers | Mapped to the strikes and maturity actually used internally to price the option, and also assigned to the Residual Risk Add-On. |
| CTP securitisation tranches with no implied volatility | Not subject to the vega risk capital requirement — but this exemption does not extend to delta or curvature risk, which still apply. |
Sourced from MAR21.26.
The Modelling Choices Banks Must Make
Two further sets of rules govern how vega sensitivities are actually computed, once the basic formula above is applied.
Sticky Strike vs Sticky Delta
When computing a first-order sensitivity for an instrument with optionality, a bank must assume the implied volatility behaves in one of two ways:
- A “sticky strike” approach — implied volatility remains constant.
- A “sticky delta” approach — implied volatility does not vary with respect to a given level of delta.
Sourced from MAR21.27.
https://www.bis.org/basel_framework/chapter/MAR/21.htm?inforce=20230101&published=20260323
Log-Normal vs Normal Distribution Assumptions
For the distribution assumptions used in pricing models when calculating vega sensitivities, the rule differs by risk class:
| Risk Class | Permitted Distribution Assumption |
| GIRR or CSR vega | Banks may use either the log-normal or the normal assumption. |
| Equity, commodity or FX vega | Banks must use the log-normal assumption only. |
| Why GIRR and CSR Get a Choice, but Other Classes Don’t The standard’s own footnote explains the reasoning. Because vega is multiplied by implied volatility in the sensitivity formula above, the resulting vega risk sensitivity for an instrument actually comes out the same whether a log-normal or normal assumption is used. Recognising the trade-off between a constrained specification and computational burden, the standard allows banks a choice for GIRR and CSR. For the other risk classes, banks must use only the log-normal assumption, in recognition that this is what aligns with common practice across jurisdictions — not because the maths differs, but for consistency with how markets in those asset classes are typically quoted and modelled. |
Sourced from MAR21.28, including its footnote.
https://www.bis.org/basel_framework/chapter/MAR/21.htm?inforce=20230101&published=20260323
Two Final Rules
If, for its own internal risk management purposes, a bank computes vega sensitivities using different definitions than the ones set out in this standard, the bank is permitted to transform those internally-computed sensitivities to derive the sensitivities required for the regulatory vega risk measure — rather than needing to run an entirely separate, parallel calculation from scratch.
Finally, and without exception: all vega sensitivities must be computed ignoring the impact of credit valuation adjustments (CVA).
| Why CVA Is Excluded Here This connects directly to the anti-double-counting theme from Article 3D. CVA risk has its own separate capital framework, and RBC25.30 established that eligible hedges already captured in the CVA capital requirement must be removed from market risk capital. Excluding CVA’s impact from vega sensitivity calculations here is the same principle applied at the sensitivity-measurement level: market risk vega should reflect the option’s own market risk, not a CVA-driven valuation effect that belongs in a different capital calculation entirely. |
Sourced from MAR21.29–MAR21.30.
https://www.bis.org/basel_framework/chapter/MAR/21.htm?inforce=20230101&published=20260323
Looking Ahead
With the sensitivity definitions for all six delta formulas and the full vega mechanics now covered, the final part of this mini-series turns to a different problem: how instruments that reference a basket of underlyings — indices, multi-underlying options, and fund investments — get broken down into individual risk factor sensitivities in the first place.
Frequently Asked Questions
What is PV01 in the FRTB sensitivities-based method?
The delta GIRR sensitivity: the change in an instrument’s market value from a 1 basis point shift in the risk-free interest rate at a given tenor, divided by 0.0001.
Why can banks choose between log-normal and normal assumptions for some risk classes but not others?
For GIRR and CSR, the resulting vega sensitivity is mathematically the same under either assumption, so the standard allows a choice to balance flexibility against computational burden. For equity, commodity and FX, only the log-normal assumption is permitted, for consistency with common market practice.
Are CVA effects included in vega sensitivity calculations?
No. All vega sensitivities must be computed ignoring the impact of credit valuation adjustments, consistent with keeping CVA risk inside its own separate capital framework rather than double-counting it in market risk.
Link to previous article
Pingback: FRTB Series 8D - MAR21: Look Through Approach