Articles 9 through 15 built delta risk one risk class at a time, each with its own dedicated bucket structure, risk weight table, and correlation formulas. Vega risk works differently, and this article is noticeably more compact as a result: rather than defining a new bucket structure seven separate times, the standard reuses delta’s buckets wholesale and layers a single, shared, liquidity-horizon-based mechanism on top, spanning every risk class at once.
Same Buckets as Delta
The chapter opens by stating this directly: the same bucket definitions used for delta risk, for each risk class, are reused for vega risk. There is no separate vega bucket structure to learn for GIRR, CSR, equity, commodity or FX — if you know a risk class’s delta buckets from Articles 9 through 15, you already know its vega buckets.
Sourced from MAR21.90–MAR21.91.
https://www.bis.org/basel_framework/chapter/MAR/21.htm?inforce=20230101&published=20260323
The Liquidity Horizon Idea, Applied to Risk Weights
For calculating weighted sensitivities under vega risk, the risk of market illiquidity is incorporated directly into the risk weight itself, by assigning each risk class its own liquidity horizon — the same liquidity horizon concept we defined back in Article 4A’s glossary: the time a bank is assumed to need to exit or hedge a position without moving market prices materially, under stressed conditions. A risk class with a longer assumed liquidity horizon is judged harder to hedge cleanly, and receives a correspondingly higher vega risk weight.
Table 13: Liquidity Horizons and Risk Weights
| Risk Class | Liquidity Horizon (days) | Risk Weight |
| GIRR | 60 | 100% |
| CSR non-securitisations | 120 | 100% |
| CSR securitisations (CTP) | 120 | 100% |
| CSR securitisations (non-CTP) | 120 | 100% |
| Equity (large cap and indices) | 20 | 77.78% |
| Equity (small cap and other sector) | 60 | 100% |
| Commodity | 120 | 100% |
| FX | 40 | 100% |
Sourced from MAR21.92 (Table 13).
https://www.bis.org/basel_framework/chapter/MAR/21.htm?inforce=20230101&published=20260323
The Formula Behind the Table
These risk weights are not independently chosen figures — every one of them is the output of a single formula, applied per risk class:
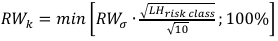
| Verifying the Table 13 Values Against the Formula Working through the formula for each risk class confirms every value in Table 13. GIRR: 55% × √(60÷10) = 55% × √6 = 134.7%, capped at the 100% ceiling. Commodity, CSR (all three sub-classes): 55% × √(120÷10) = 55% × √12 = 190.5%, also capped at 100%. FX: 55% × √(40÷10) = 55% × 2 = 110%, capped at 100%. Equity small cap: 55% × √6 = 134.7%, capped at 100%. Equity large cap is the one risk class where the formula’s raw output actually lands below the ceiling: 55% × √(20÷10) = 55% × √2 = 77.78% — exactly Table 13’s figure, with no capping needed. This is the only risk-class weight in the entire table that isn’t simply hitting the 100% ceiling, precisely because large-cap equity’s assumed 20-day liquidity horizon is short enough that the formula never pushes past 100% in the first place. |
Sourced from MAR21.92, footnote [24].
GIRR Vega Correlation: Two Decay Factors Multiplied Together
GIRR is the one risk class singled out for its own dedicated vega correlation formula, distinct from every other risk class — a direct consequence of GIRR vega’s two-dimensional structure that we established in Article 9A (option maturity × underlying residual maturity). The within-bucket correlation ρkl for aggregating vega GIRR risk positions is the product of two separate exponential decay factors, capped at 100%.

ρ_kl^(option maturity):-

ρ_kl^(underlying maturity):-

| Why This Formula Looks Familiar This decay structure — an exponential function of the absolute difference between two tenors, divided by the smaller of the two — is the same underlying shape as the GIRR delta correlation formula from Article 9B, just with α set at 1% here instead of 3%, and no 40% floor. Here, GIRR vega needs two such factors multiplied together, one for each of the two dimensions (option maturity, underlying residual maturity) that make GIRR vega risk factors genuinely two-dimensional, unlike every other risk class’s vega. |
Sourced from MAR21.93, including both sub-formulas and the combination rule.
https://www.bis.org/basel_framework/chapter/MAR/21.htm?inforce=20230101&published=20260323
Vega Correlation for Every Other Risk Class: Borrowing From Delta
For every risk class other than GIRR, the within-bucket vega correlation is built differently — not from a purely vega-specific formula, but by directly reusing the corresponding delta correlation, multiplied by a single maturity decay factor.

| The Standard’s Own Example If k is the vega risk factor from equity option X and l is the vega risk factor from equity option Y, then ρkl^(Delta) is simply the delta correlation that already applies between X and Y under the equity correlation rules from Article 13 — no new correlation value needs to be separately specified for vega. The only genuinely new ingredient is the option maturity decay factor layered on top. |
Sourced from MAR21.94, including both sub-points and the combination rule.
Cross-Bucket Vega Correlation: Reusing Delta’s Values Directly
For aggregating vega risk positions across different buckets within a risk class — for both GIRR and every other risk class — the standard makes no changes at all: the exact same cross-bucket correlation parameters γbc specified for delta correlations in each risk class’s own article (Articles 9 through 15) are reused directly for vega. The standard’s own example: the 50% cross-bucket correlation we established for delta GIRR in Article 9B is the same 50% used for aggregating vega risk sensitivities across different GIRR buckets.
Sourced from MAR21.95.
https://www.bis.org/basel_framework/chapter/MAR/21.htm?inforce=20230101&published=20260323
What Vega Reuses vs What It Redefines
| Element | Vega’s Treatment |
| Bucket structure | Identical to delta — no new buckets defined. |
| Risk weight | New: derived from a shared formula using each risk class’s liquidity horizon (Table 13). |
| Within-bucket correlation (GIRR) | New: a dedicated two-factor formula unique to GIRR vega. |
| Within-bucket correlation (all other classes) | Partially new: reuses the delta correlation, multiplied by a new maturity decay factor. |
| Cross-bucket correlation | Identical to delta — the same γbc values, for every risk class. |
Looking Ahead
Vega risk is now complete across all seven risk classes. The next article covers curvature risk — the third and final SBM risk measure — which follows a broadly similar pattern of reusing delta’s bucket structure while introducing its own risk weight and correlation treatment.
Frequently Asked Questions
Does vega risk use a different bucket structure than delta risk?
No. Vega risk reuses the exact same bucket definitions established for delta risk in each risk class’s own article — there is no separate vega bucket structure.
Why does equity (large cap) have a lower vega risk weight than every other risk class?
Its assumed liquidity horizon (20 days) is short enough that the risk weight formula’s raw output, 77.78%, never reaches the 100% ceiling that every other risk class hits. Every other risk class’s liquidity horizon produces a raw value above 100%, which then gets capped.
How is GIRR’s vega correlation different from every other risk class?
GIRR vega correlation is the product of two separate exponential decay factors (option maturity and underlying residual maturity), reflecting its two-dimensional risk factor structure. Every other risk class instead multiplies its existing delta correlation by a single maturity decay factor.
Link to previous article