Article 10 built the full non-securitisation credit spread risk framework. This article covers the first of two securitisation-related CSR risk classes: the correlation trading portfolio, or CTP — the exact test we defined back in Article 7 using MAR20.5’s four-part securitisation test, plus its non-securitisation hedges. This article shows how CTP instruments are actually capitalised once they qualify for that definition.
The short version of what follows: CTP borrows almost the entire non-securitisation framework from Article 10 wholesale, with a small number of deliberate, targeted changes. Rather than repeat everything from scratch, this article focuses on what’s genuinely new, while still giving you every number you need in full.
The Risk Factor Structure
For securitisation instruments that meet the CTP definition, delta risk factor sensitivities (the CS01) must be computed with respect to the names underlying the securitisation or nth-to-default instrument — not the tranche’s own single issuer, since a CTP instrument by definition references a basket of underlying names.
| Risk Measure | Dimensions | Structure |
| Delta | 2 | The relevant underlying credit spread curves (both bond-inferred and CDS-inferred) × five tenors: 0.5, 1, 3, 5 and 10 years. |
| Vega | 1 | Option maturity only, mapped to one or several of the same five tenors. The underlying risk factor is the implied volatility of options referencing CTP credit spreads (bond and CDS) as underlyings. |
| Curvature | 1 | The relevant underlying credit spread curve only — again treating bond and CDS curves for the same underlying name as a single combined curve, with all tenors shifted in parallel. |
| The Source Document’s Own iTraxx Example For curvature specifically, the standard gives a concrete example: the bond-inferred spread curve of a given name within an iTraxx series, and the CDS-inferred spread curve of that same underlying name, would be considered a single spread curve — exactly the same simplification we saw for non-securitisation curvature in Article 10, just applied here to names sitting underneath a CTP index or basket instrument rather than to a standalone corporate issuer. |
Sourced from MAR21.11, including all four sub-points.
The Sensitivity Formula: CS01 (A Quick Recap)
As with non-securitisations, the CTP delta sensitivity is the CS01 — the same formula we covered fully in Article 8C and recapped in Article 10. Shift the credit spread cst at tenor t by 1 basis point, and divide the resulting change in market value by 0.0001.
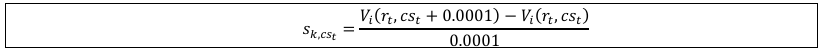
Sourced from MAR21.20.
Same Structure as Non-Securitisations, With One Exception
Sensitivities to CSR arising from the CTP and its hedges are treated as their own separate risk class, as established back in Article 7’s coverage of MAR21.1. But rather than build an entirely new bucket and correlation framework from scratch, the standard explicitly borrows the non-securitisation structure, with two changes.
- The same bucket structure and correlation structure that apply to CSR non-securitisations (MAR21.51 through MAR21.57, all covered in Article 10) apply to CTP as well — with one exception: the two index buckets (buckets 17 and 18) do not apply to CTP. Only buckets 1 through 16 are relevant here.
- The risk weights and correlation parameters that applied to CSR non-securitisations are modified for CTP, to reflect longer liquidity horizons and larger basis risk.
| Why CTP Gets Longer Liquidity Horizons Recall from Article 4A’s glossary that a liquidity horizon is the time a bank is assumed to need to exit or hedge a position without moving market prices materially, under stressed conditions. Correlation trading instruments — indices, nth-to-default baskets, and their hedges — are generally harder to unwind cleanly in a stressed market than a single plain-vanilla corporate bond or CDS, precisely because they reference a basket of underlying names whose joint behaviour becomes harder to hedge when markets are under stress. That longer assumed liquidity horizon, and the correspondingly larger basis risk between related curves, is exactly what the higher risk weights and slightly different correlation parameters below are calibrated to capture. |
Sourced from MAR21.58, including both sub-points.
The Bucket Structure (Buckets 1 Through 16 Only)
CTP uses exactly the same credit-quality-by-sector bucket definitions as Table 3 from Article 10, simply without the two index buckets. As a quick reference:
| Buckets | Credit Quality | Sectors Covered |
| 1–7 | Investment grade (IG) | Sovereigns; local government; financials; basic materials/energy/industrials; consumer goods/services; technology/telecoms; health care/utilities |
| 8 | Investment grade (IG) | Covered bonds |
| 9–15 | High yield (HY) & non-rated (NR) | Same seven sectors as buckets 1–7, at high-yield/non-rated credit quality |
| 16 | Other sector | Credit quality is not a differentiating consideration for this bucket |
See Article 10 for the complete, unabbreviated version of this table with every individual sector spelled out.
Risk Weights: Table 6
Here is where the recalibration for longer liquidity horizons becomes concrete. Every CTP risk weight is meaningfully higher than its non-securitisation counterpart from Article 10’s Table 4.
| Bucket | CTP Risk Weight (Table 6) | Non-Securitisation Risk Weight (Table 4, for comparison) |
| 1 | 4.0% | 0.5% |
| 2 | 4.0% | 1.0% |
| 3 | 8.0% | 5.0% |
| 4 | 5.0% | 3.0% |
| 5 | 4.0% | 3.0% |
| 6 | 3.0% | 2.0% |
| 7 | 2.0% | 1.5% |
| 8 | 6.0% | 2.5% |
| 9 | 13.0% | 2.0% |
| 10 | 13.0% | 4.0% |
| 11 | 16.0% | 12.0% |
| 12 | 10.0% | 7.0% |
| 13 | 12.0% | 8.5% |
| 14 | 12.0% | 5.5% |
| 15 | 12.0% | 5.0% |
| 16 | 13.0% | 12.0% |
| The Pattern Worth Noticing Some buckets more than double from non-securitisation to CTP — bucket 3 (financials, IG) goes from 5.0% to 8.0%; bucket 9 (sovereigns, HY/NR) jumps from 2.0% all the way to 13.0%. This is the “larger basis risk” language from MAR21.58 showing up directly in the numbers: the same underlying credit exposure is judged materially riskier when it is embedded in a correlation trading structure than when it is held as a plain single-name position. |
Sourced from MAR21.59 (Table 6).
https://www.bis.org/basel_framework/chapter/MAR/21.htm?inforce=20230101&published=20260323
Within-Bucket Correlation: One Change From Non-Securitisations
For aggregating CTP delta risk positions within a bucket, the correlation ρkl is derived the exact same way as for non-securitisation buckets 1–15 and index buckets 17–18 (MAR21.54 and MAR21.55 from Article 10) — with one modification. The name factor and tenor factor stay identical to the non-securitisation case. Only the basis factor — the one applying when two sensitivities relate to different curves — is adjusted downward:
| Factor | Value When Matching | Value Otherwise (Non-Sec, for Comparison) | Value Otherwise (CTP) |
| Name (same issuer?) | 100% | 35% | 35% (unchanged) |
| Tenor (same tenor?) | 100% | 65% | 65% (unchanged) |
| Basis (same curve?) | 100% | 99.90% | 99.00% (lower than non-sec) |
| ρ_kl = ρ_kl^(name) × ρ_kl^(tenor) × ρ_kl^(basis) where ρ_kl^(basis) = 99.00% (rather than 99.90%) when the two sensitivities relate to different curves |
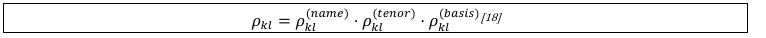
Sourced from MAR21.60, including both sub-points.
Cross-Bucket Correlation: Identical to Non-Securitisations
Unlike the within-bucket basis factor above, the cross-bucket correlation parameters γbc for aggregating CTP risk positions across different buckets are identical to the non-securitisation values we covered in Article 10 — the same two-factor rating/sector structure, and the same full Table 5 matrix. Nothing changes here for CTP.
Sourced from MAR21.61.
https://www.bis.org/basel_framework/chapter/MAR/21.htm?inforce=20230101&published=20260323
CTP vs Non-Securitisations: The Complete Comparison
| Element | Non-Securitisations (Article 10) | CTP (This Article) |
| Bucket structure | 18 buckets (including index buckets 17–18) | 16 buckets (index buckets excluded) |
| Risk weights | Table 4 values | Table 6 values — meaningfully higher across the board |
| Name correlation factor | 100% / 35% (or 80% for index buckets) | 100% / 35% (unchanged) |
| Tenor correlation factor | 100% / 65% | 100% / 65% (unchanged) |
| Basis correlation factor | 100% / 99.90% | 100% / 99.00% (lower) |
| Cross-bucket correlation | Table 5, two-factor structure | Identical to non-securitisations |
Looking Ahead
With CTP now fully covered, the next two articles turn to the more complex securitisation category: instruments that do not meet the CTP definition at all. This is the densest bucket structure in the entire Sensitivities-Based Method — a 25-bucket matrix across three credit quality tiers and eight sector types — dense enough that we are splitting it into two parts.
Frequently Asked Questions
Which buckets apply to the correlation trading portfolio?
Buckets 1 through 16 — the same credit-quality-by-sector structure as CSR non-securitisations, but excluding the two index buckets (17 and 18), which do not apply to CTP.
Why are CTP risk weights higher than non-securitisation risk weights for the same bucket?
The risk weights are calibrated to reflect the longer liquidity horizons and larger basis risk associated with correlation trading instruments, which are generally harder to unwind cleanly in stressed markets than single-name positions.
What changes in the correlation formula between CTP and non-securitisations?
Only the basis factor, which applies when two sensitivities relate to different curves — it drops from 99.90% for non-securitisations to 99.00% for CTP. The name factor, tenor factor, and all cross-bucket correlations remain identical.
Link to previous article