Article 11 covered the correlation trading portfolio. This article, and Part B that follows it, cover the other securitisation category: instruments that do not meet the CTP definition at all — ordinary RMBS, CMBS, ABS and CLO tranches. This is genuinely the densest bucket structure anywhere in the Sensitivities-Based Method, which is why we are splitting it in two: this article covers the risk factor definitions and the full 25-bucket structure, and Part B covers the complete risk weight and correlation tables.
The Risk Factor Structure — A Genuinely Different Starting Point
Before the dimensional structure, there is a conceptual difference from Article 11 worth understanding first. For securitisation instruments that do not meet the CTP definition, delta sensitivities (the CS01) must be calculated with respect to the spread of the tranche itself, rather than the spread of the names underlying the instrument.
| Tranche Spread vs Underlying Names: Why This Matters In Article 11, CTP delta sensitivities were computed against the credit spread curves of the individual names sitting underneath a CTP index or basket — a genuine look-through to constituent exposures. Non-CTP securitisations work the opposite way: the tranche itself trades with its own observable credit spread, and that tranche-level spread — not the spreads of the underlying mortgages or loans packaged inside it — is what generates the sensitivity. This makes intuitive sense once you think about it: a CTP instrument like an index or nth-to-default basket is priced off the correlation and behavior of its named constituents. An RMBS or CLO tranche, by contrast, trades in the market as its own instrument with its own spread — a AAA-rated senior tranche and a BB-rated mezzanine tranche of the same underlying mortgage pool have entirely different market spreads, reflecting their different position in the capital structure, not just the pool’s average characteristics. |
| Risk Measure | Dimensions | Structure |
| Delta | 2 | Tranche credit spread curves × five tenors: 0.5, 1, 3, 5 and 10 years. |
| Vega | 1 | Option maturity only, mapped to one or several of the same five tenors. The underlying risk factor is the implied volatility of options referencing non-CTP credit spreads (bond and CDS) as underlyings. |
| Curvature | 1 | The relevant tranche credit spread curve only — again treating bond and CDS curves for the same tranche as a single combined curve, with all tenors shifted in parallel. |
| The Source Document’s Own Spanish RMBS Example For curvature, the standard illustrates the bond/CDS combination rule with a specific example: the bond-inferred spread curve of a given Spanish residential mortgage-backed security tranche, and the CDS-inferred spread curve of that same Spanish RMBS tranche, would be considered a single spread curve. This mirrors the identical simplification we saw for non-securitisation curvature in Article 10 and CTP curvature in Article 11 — the pattern holds across all three CSR sub-classes, just applied to a different underlying spread each time. |
Sourced from MAR21.10, including all four sub-points.
The Sensitivity Formula: CS01 (A Quick Recap)
As with the other two CSR sub-classes, the delta sensitivity here is the CS01, covered in full in Article 8C: shift the credit spread cst at tenor t by 1 basis point, and divide the resulting change in the tranche’s market value by 0.0001.
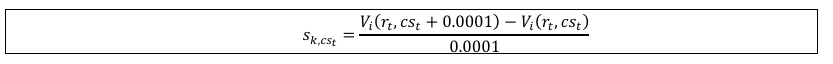
The Bucket Structure: 25 Buckets Across Three Credit Quality Tiers
For delta CSR securitisations outside the CTP, buckets are defined along two dimensions — credit quality and sector — exactly as with non-securitisations in Article 10, but with a wider sector list built specifically for securitisation products, and a third credit quality tier. Sensitivities must first be assigned to one of these 25 buckets before a risk weight is applied.
| Bucket | Credit Quality | Sector |
| 1 | Senior investment grade (IG) | RMBS — Prime |
| 2 | Senior investment grade (IG) | RMBS — Mid-prime |
| 3 | Senior investment grade (IG) | RMBS — Sub-prime |
| 4 | Senior investment grade (IG) | CMBS |
| 5 | Senior investment grade (IG) | ABS — Student loans |
| 6 | Senior investment grade (IG) | ABS — Credit cards |
| 7 | Senior investment grade (IG) | ABS — Auto |
| 8 | Senior investment grade (IG) | CLO (non-CTP) |
| 9 | Non-senior IG | RMBS — Prime |
| 10 | Non-senior IG | RMBS — Mid-prime |
| 11 | Non-senior IG | RMBS — Sub-prime |
| 12 | Non-senior IG | CMBS |
| 13 | Non-senior IG | ABS — Student loans |
| 14 | Non-senior IG | ABS — Credit cards |
| 15 | Non-senior IG | ABS — Auto |
| 16 | Non-senior IG | CLO (non-CTP) |
| 17 | High yield & non-rated | RMBS — Prime |
| 18 | High yield & non-rated | RMBS — Mid-prime |
| 19 | High yield & non-rated | RMBS — Sub-prime |
| 20 | High yield & non-rated | CMBS |
| 21 | High yield & non-rated | ABS — Student loans |
| 22 | High yield & non-rated | ABS — Credit cards |
| 23 | High yield & non-rated | ABS — Auto |
| 24 | High yield & non-rated | CLO (non-CTP) |
| 25 | Other sector | Credit quality is not a differentiating consideration for this bucket |
| Reading the Structure: Three Tiers, Eight Sectors, One Catch-All The pattern here is genuinely simple once you see it, despite the size of the table: eight sectors (RMBS split three ways by prime/mid-prime/sub-prime, plus CMBS, three types of ABS, and CLO) repeated identically across three credit quality tiers — senior investment grade, non-senior investment grade, and high yield/non-rated — giving 8 × 3 = 24 buckets, plus bucket 25 as the catch-all for anything that cannot be classified into one of those eight sectors. Notice the distinction between buckets 1–8 and 9–16: both tiers are investment grade, but bucket 1–8 is specifically senior tranches, while 9–16 is non-senior (mezzanine or subordinated) investment-grade tranches — a distinction that did not exist in the non-securitisation bucket structure from Article 10, reflecting how much a tranche’s position in the capital structure matters for securitisation risk specifically. |
Sourced from MAR21.62 (Table 7) and footnote [19].
https://www.bis.org/basel_framework/chapter/MAR/21.htm?inforce=20230101&published=20260323
Assigning a Tranche to a Sector
To assign a risk exposure to a sector, banks must rely on a classification that is commonly used in the market for grouping tranches by type — the same market-based classification principle we saw for non-securitisation issuers in Article 10, just applied to tranche type rather than issuer industry. Each tranche must be assigned to one of the sector buckets in Table 7 above. Where a bank genuinely cannot assign a tranche to a sector this way, that risk position must default to the other sector bucket — bucket 25.
Sourced from MAR21.63, including both sub-points.
Risk Weights: The Base Table, Then Two Scaling Rules
Rather than specifying all 25 risk weights individually, the standard defines only the eight senior investment-grade weights directly, then derives the remaining 16 (excluding bucket 25) by simple multiplication.
Table 8: Buckets 1–8 (Senior Investment Grade)
| Bucket | Risk Weight |
| 1 | 0.9% |
| 2 | 1.5% |
| 3 | 2.0% |
| 4 | 2.0% |
| 5 | 0.8% |
| 6 | 1.2% |
| 7 | 1.2% |
| 8 | 1.4% |
Sourced from MAR21.64 (Table 8).
Buckets 9–16 (Non-Senior IG): Multiply by 1.25
The risk weights for buckets 9 through 16 are equal to the corresponding risk weights for buckets 1 through 8, scaled up by a multiplication of 1.25. The standard gives its own example: the risk weight for bucket 9 (non-senior IG, RMBS Prime) is 1.25 × 0.9% = 1.125%, corresponding to bucket 1’s senior IG RMBS Prime weight of 0.9%.
Sourced from MAR21.65.
Buckets 17–24 (High Yield & Non-Rated): Multiply by 1.75
Similarly, the risk weights for buckets 17 through 24 are equal to the corresponding risk weights for buckets 1 through 8, scaled up by a multiplication of 1.75. The standard’s own example: the risk weight for bucket 17 (HY/NR, RMBS Prime) is 1.75 × 0.9% = 1.575%.
Sourced from MAR21.66.
Bucket 25 (Other Sector): Flat 3.5%
The risk weight for bucket 25 is set at a flat 3.5%, regardless of the underlying instrument type.
Sourced from MAR21.67.
The Complete 25-Bucket Risk Weight Table
| Bucket | Sector | Credit Quality | Risk Weight |
| 1 | RMBS — Prime | Senior IG | 0.9% |
| 2 | RMBS — Mid-prime | Senior IG | 1.5% |
| 3 | RMBS — Sub-prime | Senior IG | 2.0% |
| 4 | CMBS | Senior IG | 2.0% |
| 5 | ABS — Student loans | Senior IG | 0.8% |
| 6 | ABS — Credit cards | Senior IG | 1.2% |
| 7 | ABS — Auto | Senior IG | 1.2% |
| 8 | CLO (non-CTP) | Senior IG | 1.4% |
| 9 | RMBS — Prime | Non-senior IG | 1.125% |
| 10 | RMBS — Mid-prime | Non-senior IG | 1.875% |
| 11 | RMBS — Sub-prime | Non-senior IG | 2.5% |
| 12 | CMBS | Non-senior IG | 2.5% |
| 13 | ABS — Student loans | Non-senior IG | 1.0% |
| 14 | ABS — Credit cards | Non-senior IG | 1.5% |
| 15 | ABS — Auto | Non-senior IG | 1.5% |
| 16 | CLO (non-CTP) | Non-senior IG | 1.75% |
| 17 | RMBS — Prime | High yield & non-rated | 1.575% |
| 18 | RMBS — Mid-prime | High yield & non-rated | 2.625% |
| 19 | RMBS — Sub-prime | High yield & non-rated | 3.5% |
| 20 | CMBS | High yield & non-rated | 3.5% |
| 21 | ABS — Student loans | High yield & non-rated | 1.4% |
| 22 | ABS — Credit cards | High yield & non-rated | 2.1% |
| 23 | ABS — Auto | High yield & non-rated | 2.1% |
| 24 | CLO (non-CTP) | High yield & non-rated | 2.45% |
| 25 | Other sector | — | 3.5% |
| Values Derived, Not Independently Sourced Only the eight values in Table 8 (buckets 1–8) are stated directly in the source document. Every value for buckets 9–24 in the table above is calculated by applying the 1.25× or 1.75× multiplier from MAR21.65 and MAR21.66 — shown here in full so this article stands as a complete reference, but derived rather than independently specified figures. |
Correlation Within a Bucket
For aggregating non-CTP securitisation risk positions within a bucket, the correlation parameter ρkl between two weighted sensitivities is again built from three multiplicative factors — structurally similar to the non-securitisation and CTP formulas from Articles 10 and 11, but with meaningfully different values and a different first factor entirely.
| Factor | Value When Matching | Value Otherwise |
| Name/tranche (same tranche?) | 100% where the two sensitivities relate to the same securitisation tranche, defined as more than 80% overlap in notional terms | 40% otherwise |
| Tenor (same tenor?) | 100% if the two tenors are identical | 80% otherwise |
| Basis (same curve?) | 100% if the two sensitivities relate to the same curve | 99.90% otherwise |

| How This Differs From Non-Securitisations and CTP The first factor here is genuinely different in kind, not just in value, from the “name” factor we saw in Articles 10 and 11. Non-securitisation and CTP correlations both hinge on whether two sensitivities relate to the same issuer name. Non-CTP securitisation correlation instead hinges on whether two sensitivities relate to the same tranche — defined precisely as more than 80% overlap in notional terms, an explicit quantitative threshold rather than a simple same/different test. The tenor factor is also notably lower here (80% when tenors differ) than the 65% used for non-securitisations and CTP — meaning non-CTP securitisation sensitivities at different tenors are treated as more correlated with each other than the equivalent case elsewhere in CSR. The basis factor (99.90% when curves differ) is unchanged from the non-securitisation case. |
Sourced from MAR21.68, including all three sub-points and the formula.
The Other Sector Bucket Exception
As with the equivalent bucket in Article 10, the correlation formula above does not apply to the other sector bucket — bucket 25. Instead, this bucket falls back to the same conservative, no-diversification aggregation method we have now seen twice before.
For delta and vega risk within bucket 25, the risk position is the sum of the absolute values of the net weighted sensitivities allocated to that bucket:

For curvature risk within bucket 25, the risk position takes the larger of the summed positive CVRk+ values or the summed positive CVRk− values:
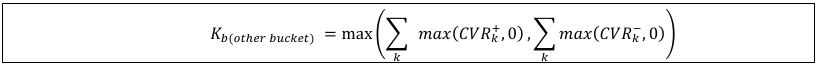
| A Note on the Source Text Itself In stating the curvature formula for this bucket, the source document’s own cross-reference reads “bucket 16” rather than “bucket 25.” Given the surrounding context is unambiguously about the non-CTP securitisation other sector bucket — which this article’s Table 7 defines as bucket 25, not bucket 16 — this reads as a drafting inconsistency in the original text (bucket 16 is the equivalent other-sector bucket in the non-securitisation framework from Article 10, so the reference appears to be a carried-over label). We are flagging this discrepancy transparently rather than silently correcting it, since our own rule is not to make assumptions about the source document without calling them out. |
Sourced from MAR21.69, including both formulas, with the discrepancy noted above.
Correlation Across Buckets
This is where non-CTP securitisation diverges most sharply from both non-securitisations and CTP. Rather than a graduated Table 5-style matrix of rating and sector correlations, the cross-bucket structure here uses just two flat values.
| Bucket Pairing | Cross-Bucket Correlation (γbc) |
| Any two buckets among buckets 1 through 24 | 0% |
| The other sector bucket (25) against any of buckets 1 through 24 | 100% |
| What a 0% Cross-Bucket Correlation Actually Means Setting γbc at 0% between any two of buckets 1 through 24 means the standard assumes full diversification benefit between different non-CTP securitisation buckets — a risk position in bucket 3 (senior IG CMBS) is treated as having no correlation at all with a risk position in bucket 14 (non-senior IG ABS credit cards) when aggregating across buckets. This is a more generous diversification assumption than either non-securitisations or CTP, both of which use graduated correlations from Table 5 ranging from 0% to 75% depending on the specific bucket pairing. Bucket 25 sits at the opposite extreme: a 100% correlation against every other bucket means no diversification benefit at all is recognised for the other sector bucket. Bucket-level capital requirements simply get summed directly into the overall risk class capital requirement wherever bucket 25 is involved — the same fully additive, no-hedging-recognised treatment the standard applies whenever an exposure cannot be properly classified. |
Sourced from MAR21.70–MAR21.71, including the explicit statement that bucket-level capital requirements are simply summed with no diversification or hedging effects recognised for bucket 25.
The Three CSR Sub-Classes: A Complete Comparison
With all three credit spread risk sub-classes now fully built across Articles 10, 11, and this two-part article, here is the complete picture of how they relate to each other.
| Element | Non-Securitisations | CTP | Non-CTP Securitisations |
| Number of buckets | 18 | 16 | 25 |
| Delta sensitivity basis | Issuer name | Underlying names | Tranche itself |
| Within-bucket “identity” factor | Name: 100% / 35% (or 80% index) | Name: 100% / 35% | Tranche: 100% / 40% (>80% notional overlap test) |
| Within-bucket tenor factor | 100% / 65% | 100% / 65% | 100% / 80% |
| Within-bucket basis factor | 100% / 99.90% | 100% / 99.00% | 100% / 99.90% |
| Cross-bucket correlation | Graduated, Table 5 (0–75%) | Identical to non-sec (Table 5) | Flat 0% (or 100% for other-sector bucket) |
| Other-sector bucket treatment | Bucket 16: no diversification | N/A (borrows non-sec structure) | Bucket 25: no diversification |
Looking Ahead
Credit spread risk is now complete across all three sub-classes. The next article moves to equity risk — a three-dimensional bucket structure combining market capitalisation, economy, and sector, which we already caught a glimpse of in Table 9 while confirming where this article’s content ends.
Frequently Asked Questions
How are the risk weights for buckets 9 through 24 calculated?
They are derived from the eight senior investment-grade weights in Table 8: buckets 9–16 (non-senior IG) multiply the corresponding Table 8 weight by 1.25, and buckets 17–24 (high yield/non-rated) multiply it by 1.75.
What counts as “the same tranche” for correlation purposes in non-CTP securitisations?
More than 80% overlap in notional terms — an explicit quantitative threshold, rather than the simpler same-issuer test used for non-securitisations and CTP.
Why is the cross-bucket correlation for non-CTP securitisations so much lower than for non-securitisations?
The standard sets it at a flat 0% between any two of buckets 1–24, recognising full diversification benefit across different securitisation buckets — a more generous assumption than the graduated 0–75% range used for non-securitisations and CTP. The other sector bucket (25) is the exception, at 100% correlation with no diversification recognised.
Link to previous article
Pingback: FRTB Series 13: Equity: Bucktes, Risk Weights & Correlation