With credit spread risk complete across Articles 10, 11 and 12, we move to the fourth risk class: equity risk. This is the first risk class in this series whose bucket structure is genuinely three-dimensional — market capitalisation, economy, and sector all at once — but it fits comfortably in a single article.
The Risk Factor Structure
Equity delta, vega and curvature risk factors are defined more narrowly than GIRR or CSR, with equity repo rates treated as a genuinely separate risk factor from equity spot prices.
| Risk Measure | Risk Factors |
| Delta | All equity spot prices, and all equity repurchase agreement (repo) rates — two separate sets of risk factors. |
| Vega | The implied volatilities of options referencing equity spot prices as underlyings, mapped along one dimension: the option’s maturity, using five tenors (0.5, 1, 3, 5 and 10 years). There is no vega risk capital requirement for equity repo rates. |
| Curvature | All equity spot prices only. There is no curvature risk capital requirement for equity repo rates. |
A pattern worth noting before we go further: equity repo rates generate a delta capital requirement, but never a vega or curvature capital requirement — only equity spot prices are subject to all three risk measures.
| A Note on the Source Text Itself In listing the curvature equity sub-points, the source document labels both items “(a)” — “the equity curvature risk factors are all the equity spot prices” and “there is no curvature risk capital requirement for equity repo rates” are both marked (a), where the second should logically be (b). This reads as a minor numbering typo in the original text rather than a substantive drafting issue, and does not affect the meaning of either sub-point. We are flagging it transparently, consistent with our approach to the bucket-numbering discrepancy noted in Article 12B. |
Sourced from MAR21.12, including sub-points (1) through (3).
The Sensitivity Formulas (A Quick Recap)
Both equity delta formulas were covered in full in Article 8C, so we won’t repeat the derivations — but for completeness, here they are again.

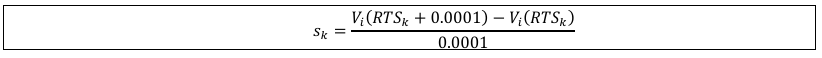
Sourced from MAR21.21–MAR21.22.
The Bucket Structure: Three Dimensions at Once
For delta equity risk, buckets are set along three dimensions simultaneously — market capitalisation, economy, and sector — giving 13 buckets in total. Every equity risk sensitivity or exposure must first be assigned to one of these 13 buckets before a risk weight is applied.
| Bucket | Market Cap | Economy | Sector |
| 1 | Large | Emerging market | Consumer goods/services, transportation/storage, admin/support services, healthcare, utilities |
| 2 | Large | Emerging market | Telecommunications, industrials |
| 3 | Large | Emerging market | Basic materials, energy, agriculture, manufacturing, mining and quarrying |
| 4 | Large | Emerging market | Financials (incl. government-backed), real estate activities, technology |
| 5 | Large | Advanced economy | Consumer goods/services, transportation/storage, admin/support services, healthcare, utilities |
| 6 | Large | Advanced economy | Telecommunications, industrials |
| 7 | Large | Advanced economy | Basic materials, energy, agriculture, manufacturing, mining and quarrying |
| 8 | Large | Advanced economy | Financials (incl. government-backed), real estate activities, technology |
| 9 | Small | Emerging market | All sectors described under buckets 1, 2, 3 and 4 |
| 10 | Small | Advanced economy | All sectors described under buckets 5, 6, 7 and 8 |
| 11 | — | — | Other sector — market cap and economy are not differentiating for this bucket |
| 12 | Large | Advanced economy | Equity indices (non-sector specific) |
| 13 | — | — | Other equity indices (non-sector specific) |
Sourced from MAR21.72 (Table 9), including footnote [20].
Defining Each Dimension
Market Capitalisation
Market capitalisation is defined as the sum of the market capitalisations, based on market value, of the total outstanding shares issued by the same listed legal entity — or, where the listed entity is a parent company of a group of legal entities, the total outstanding shares issued by that group, across all stock markets globally. One restriction is stated explicitly: under no circumstances should the market capitalisations of multiple separate, related listed entities be added together to determine whether a listed entity counts as large or small market cap.
The large/small threshold itself is a single, simple number: large market cap is defined as a market capitalisation equal to or greater than USD 2 billion, and small market cap is anything below that.
Sourced from MAR21.73–MAR21.74.
Advanced Economy
The standard names the advanced economies directly, rather than leaving this to interpretation: Canada, the United States, Mexico, the euro area, the non-euro area western European countries (the United Kingdom, Norway, Sweden, Denmark and Switzerland), Japan, Oceania (Australia and New Zealand), Singapore, and Hong Kong SAR. Any economy not on this list is treated as an emerging market economy for bucket assignment purposes.
Sourced from MAR21.75.
Sector Assignment
As with the credit spread risk classes before it, banks must rely on a classification commonly used in the market for grouping issuers by industry sector — not a bespoke internal system. Each issuer must be assigned to one of the sector buckets in Table 9, and all issuers from the same industry must be assigned consistently to the same sector. Where a bank genuinely cannot classify an issuer this way, the exposure defaults to the other sector bucket (bucket 11).
One further rule handles a genuinely tricky case: for multinational, multi-sector equity issuers — companies operating across several countries and several industries at once — the allocation to a particular bucket must be based on the issuer’s most material region and sector, rather than an average or a formal headquarters location.
Sourced from MAR21.76, including all three sub-points.
Risk Weights: Table 10
For calculating weighted sensitivities, each of the 13 buckets carries two separate risk weights: one applied to equity spot price sensitivities, and one applied to equity repo rate sensitivities. Notice that the repo rate risk weight is always exactly one-hundredth of the spot price risk weight for the same bucket.
| Bucket | Risk Weight — Equity Spot | Risk Weight — Equity Repo |
| 1 | 55% | 0.55% |
| 2 | 60% | 0.60% |
| 3 | 45% | 0.45% |
| 4 | 55% | 0.55% |
| 5 | 30% | 0.30% |
| 6 | 35% | 0.35% |
| 7 | 40% | 0.40% |
| 8 | 50% | 0.50% |
| 9 | 70% | 0.70% |
| 10 | 50% | 0.50% |
| 11 | 70% | 0.70% |
| 12 | 15% | 0.15% |
| 13 | 25% | 0.25% |
| Reading the Pattern in the Weights Emerging market buckets (1–4) generally carry higher weights than their advanced-economy counterparts (5–8) in the same sector row — bucket 2 (large cap, emerging market, telecoms/industrials) at 60% versus bucket 6 (large cap, advanced economy, same sectors) at 35%. Small market cap buckets (9 and 10) carry the highest non-index weights of all, at 70% and 50% respectively — smaller, less liquid names are judged riskier than large caps in the same economy grouping. The two index buckets (12 and 13) carry by far the lowest weights, 15% and 25%, reflecting the diversification already embedded in an index instrument. |
Sourced from MAR21.77 (Table 10).
Correlation Within a Bucket
This is the most layered correlation structure of any risk class covered so far, built from four distinct rules rather than a single multiplicative formula.
Rule 1: Spot vs Repo, Same Issuer
Where one sensitivity is to an equity spot price and the other to an equity repo rate, and both relate to the same equity issuer name, the correlation parameter ρkl is set at 99.90%.
Rule 2: Spot vs Spot, by Bucket Group
Where both sensitivities are to equity spot price, within the same bucket, the correlation depends on which of five bucket groups the pair falls into:
| Bucket Group | Correlation |
| Large market cap, emerging market economy (buckets 1, 2, 3 or 4) | 15% |
| Large market cap, advanced economy (buckets 5, 6, 7 or 8) | 25% |
| Small market cap, emerging market economy (bucket 9) | 7.5% |
| Small market cap, advanced economy (bucket 10) | 12.5% |
| Either index bucket (12 or 13) | 80% |
Rule 3: Repo vs Repo, Same Bucket Groups
The identical correlation values from Rule 2 above apply where both sensitivities are to equity repo rates instead of equity spot prices.
Rule 4: Spot vs Repo, Different Issuer
Where one sensitivity is to an equity spot price and the other to an equity repo rate, but the two sensitivities relate to different equity issuer names, the correlation parameter is the relevant Rule 2 value multiplied by 99.90%.
| Rule 1 (spot/repo, same issuer): ρ_kl = 99.90% Rule 2 (spot/spot, by bucket group): ρ_kl = [15% / 25% / 7.5% / 12.5% / 80%] Rule 3 (repo/repo, by bucket group): ρ_kl = [same values as Rule 2] Rule 4 (spot/repo, different issuer): ρ_kl = [Rule 2 value] × 99.90% |
Sourced from MAR21.78, including all four sub-points.
The Other Sector Bucket Exception
None of the four correlation rules above apply to bucket 11, the other sector bucket. As with the equivalent buckets in Articles 10 and 12B, this bucket falls back to a conservative, no-diversification aggregation method.
For delta and vega risk within bucket 11, the risk position is the sum of the absolute values of the net weighted sensitivities allocated to that bucket:

For curvature risk within bucket 11, the risk position takes the larger of the summed positive CVRk+ values or the summed positive CVRk− values:
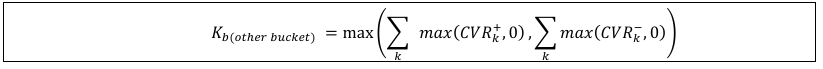
Sourced from MAR21.79, including both sub-points and formulas.
Correlation Across Buckets 1 Through 13
For aggregating delta equity risk positions across different buckets, the cross-bucket correlation parameter γbc follows four specific rules, applied in order:
| # | Rule |
| 1 | 15% if both bucket b and bucket c fall within buckets 1 to 10. |
| 2 | 0% if either bucket b or bucket c is bucket 11 (the other sector bucket). |
| 3 | 75% if bucket b and bucket c are buckets 12 and 13 (one is the large-cap advanced-economy index bucket, the other is the general index bucket). |
| 4 | 45% otherwise — covering, for example, any pairing between a non-index bucket (1–10) and an index bucket (12 or 13). |
Sourced from MAR21.80, including all four sub-points.
https://www.bis.org/basel_framework/chapter/MAR/21.htm?inforce=20230101&published=20260323
Looking Ahead
Equity risk is now complete. The next article turns to commodity risk — the fifth risk class, with its own 11-bucket structure grouping commodities by shared physical and market characteristics, and a large intra-bucket correlation matrix.
Frequently Asked Questions
What are the three dimensions of the equity risk bucket structure?
Market capitalisation (large or small, using a USD 2 billion threshold), economy (advanced or emerging market, based on a named list of advanced economies), and sector (based on common market classification).
Do equity repo rates face vega and curvature capital requirements?
No. Equity repo rates only generate a delta capital requirement. Vega and curvature capital requirements apply only to equity spot prices.
How are multinational, multi-sector companies assigned to an equity bucket?
Based on the issuer’s most material region and sector of operation, rather than an average across all its activities or its formal headquarters location.
Link to previous article
Pingback: FRTB Series 14 - MAR21: Commodity Risk - RW and Correlation