Articles 8A through 8D built the complete SBM engine — the formulas, the sensitivity mechanics, the look-through rules. From here, this series moves risk class by risk class, supplying each engine with its specific fuel: risk factor definitions, buckets, risk weights and correlations. We start with General Interest Rate Risk, or GIRR — for most banks, one of the largest and most closely watched risk classes in the entire framework.
GIRR splits naturally into two parts. This article, Part A, covers what actually counts as a GIRR risk factor — the definitional groundwork MAR21.8 sets out in real depth, genuinely the densest risk factor section anywhere in MAR21 — plus a brief recap of the PV01 sensitivity formula from Article 8C. Part B covers the currency buckets, risk weights and correlation structure used to aggregate those sensitivities into a capital number.
Two Dimensions of Delta GIRR Risk Factors
Delta GIRR risk factors are defined along two dimensions at once: a risk-free yield curve for each currency in which interest rate-sensitive instruments are denominated, and a fixed set of ten tenors to which risk factors on that curve are assigned.
| The Ten Prescribed GIRR Tenors |
| 0.25 years |
| 0.5 years |
| 1 year |
| 2 years |
| 3 years |
| 5 years |
| 10 years |
| 15 years |
| 20 years |
| 30 years |
How the Risk-Free Yield Curve Is Actually Constructed
The standard sets a clear preference order. The risk-free yield curve per currency should ideally be built from money market instruments held in the trading book with the lowest credit risk — overnight index swaps (OIS) are the example given — or alternatively, from one or more market-implied swap curves the bank already uses to mark its own positions to market, such as interbank offered rate (IBOR) swap curves.
Where data on those market-implied swap curves is insufficient, the risk-free yield curve may instead be derived from the most appropriate sovereign bond curve for that currency. This fallback comes with a consequence worth sitting with:
| Why the Sovereign Bond Fallback Isn’t a Free Pass A bond yield can be thought of as splitting into two pieces: y = r + cs — a risk-free rate component (r) and a credit spread component (cs). GIRR only wants exposure to the pure risk-free piece. If a bank uses a sovereign bond curve as its risk-free proxy but cannot actually perform that decomposition, the sensitivity to y does not simply get treated as GIRR risk. Instead, it gets allocated to both the GIRR and the CSR risk classes, using the standard’s risk factor and sensitivity definitions for each. This is a deliberate safeguard, not an accident: it stops a bank from using an imprecise risk-free proxy as a way to quietly under-capture credit spread risk. Using swap curves for bond-derived sensitivities in the GIRR calculation also does not remove the separate requirement to capture basis risk between bond curves and credit default swap curves within the CSR risk class itself. |
One further rule governs when two curves count as genuinely distinct for this purpose: an OIS curve (such as Eonia, or a newer benchmark rate) and an IBOR swap curve (such as three-month Euribor) must always be treated as two different curves. Two IBOR curves at different maturities — three-month Euribor and six-month Euribor, for instance — must also be treated as two different curves. And an onshore currency curve and its offshore equivalent — onshore Indian rupee versus offshore Indian rupee, for example — must likewise be treated as two different curves.
Sourced from MAR21.8(1), including sub-points (a) through (c).
https://www.bis.org/basel_framework/chapter/MAR/21.htm?inforce=20230101&published=20260323
The Inflation Risk Factor
GIRR delta risk factors also include a flat curve of market-implied inflation rates for each currency — flat meaning its term structure is not itself recognised as a separate risk factor. Sensitivity to this inflation rate, arising from exposure to implied coupons in an inflation-linked instrument, gives rise to its own specific capital requirement. All inflation risks for a given currency are aggregated into one number via a simple sum.
This risk factor only becomes relevant for an instrument when a cash flow is functionally dependent on a measure of inflation — for example, where the notional amount or an interest payment moves with a consumer price index. Ordinary GIRR risk factors continue to apply to such an instrument regardless. Inflation rate risk is captured in addition to the instrument’s ordinary interest rate sensitivity, which is separately allocated within the term structure of the relevant risk-free yield curve in the same currency.
Sourced from MAR21.8(2), including sub-points (a) through (c).
https://www.bis.org/basel_framework/chapter/MAR/21.htm?inforce=20230101&published=20260323
The Cross-Currency Basis Risk Factor
GIRR delta risk factors also include one of two possible cross-currency basis risk factors for each currency — again with no term structure, meaning both possible basis curves are treated as flat. The two available factors are a currency’s basis over USD, or its basis over EUR.
| The Standard’s Own Example An AUD-denominated bank trading a JPY/USD cross-currency basis swap would have a sensitivity to the JPY/USD basis, but not to a JPY/EUR basis — the bank only picks up exposure to the specific basis pair it actually transacted in. |
Where a cross-currency basis does not relate to either USD or EUR, it must still be computed against one of the two — basis over USD or basis over EUR, but never both at once. Ordinary GIRR risk factors continue to apply to such an instrument regardless. As with inflation risk, cross-currency basis risk is captured in addition to the instrument’s ordinary interest rate sensitivity, separately allocated within the relevant risk-free yield curve’s term structure.
Sourced from MAR21.8(3), including sub-points (a) through (c) and footnote [4].
Vega GIRR Risk Factors
Within each currency, GIRR vega risk factors are the implied volatilities of options referencing GIRR-sensitive underlyings, defined along two dimensions:
- The maturity of the option itself, mapped to one or several of five prescribed tenors: 0.5, 1, 3, 5 and 10 years.
- The residual maturity of the option’s underlying at the option’s own expiry date, mapped to two (or one) of the same five tenors: 0.5, 1, 3, 5 and 10 years.
| The Forward-Starting Cap Example, Explained The standard’s own footnote uses a genuinely useful example. A forward-starting cap, starting in 12 months and lasting a further 12 months, is actually made up of four consecutive caplets on three-month USD Libor — four independent options with expiry dates at 12, 15, 18 and 21 months. Every one of these caplets shares the same underlying, three-month USD Libor, whose residual maturity is always three months after its own option’s expiry date. So the implied volatilities for this single forward-starting cap must be mapped along both dimensions at once: option maturity (12, 15, 18 and 21 months for the four caplets) and the underlying’s residual maturity (three months, consistently, for all four). A single instrument can therefore generate sensitivities spread across several maturity-tenor combinations, not just one. |
Sourced from MAR21.8(4), including footnote [5] in full.
Curvature GIRR Risk Factors
Curvature GIRR works differently from both delta and vega: it is defined along only one dimension — the constructed risk-free yield curve per currency, with no term structure decomposition at all. Every curve for a given currency must be shifted together, at the same time, to compute that currency’s curvature risk capital requirement.
| The Standard’s Own Euro Example For the euro specifically, the Eonia curve, the three-month Euribor curve, and the six-month Euribor curve must all be shifted simultaneously to compute the euro-relevant risk-free yield curve curvature capital requirement. When calculating the underlying sensitivities, every tenor defined for delta GIRR is shifted in parallel, together, rather than one at a time. |
One further, important carve-out: there is no curvature risk capital requirement at all for inflation risk or cross-currency basis risk. Both of those risk factors are captured only under delta GIRR — they never generate a curvature charge.
Sourced from MAR21.8(5), including sub-points (a) and (b).
One Rule That Applies Across All Three
The sovereign bond fallback treatment we covered above for delta GIRR — including the y = r + cs decomposition requirement — applies equally to vega GIRR and curvature GIRR risk factors, not just to delta.
Sourced from MAR21.8(6).
https://www.bis.org/basel_framework/chapter/MAR/21.htm?inforce=20230101&published=20260323
How Risk Factors Get Assigned to Tenors
A footnote to this paragraph clarifies the mechanics of mapping a risk factor to the prescribed tenors: this assignment should be performed using linear interpolation, or a method that is most consistent with the pricing functions used by the bank’s own independent risk control function to report market risks or P&L to senior management — the same anchoring principle to genuine internal risk infrastructure that we saw throughout Article 8C.
Sourced from MAR21.8, footnote [3].
A Quick Recap: The GIRR Sensitivity Formula
We covered the full PV01 formula in detail back in Article 8C, so we won’t repeat the derivation here — but for completeness within this article, the GIRR sensitivity is defined as the PV01: shift the risk-free interest rate rt at tenor t by 1 basis point (0.0001 in absolute terms), and divide the resulting change in the instrument’s market value by 0.0001.
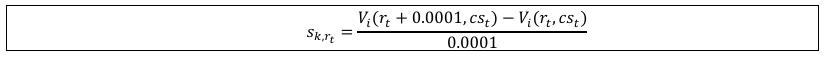
Sourced from MAR21.19 — see Article 8C for the complete treatment alongside the other five delta sensitivity formulas.
https://www.bis.org/basel_framework/chapter/MAR/21.htm?inforce=20230101&published=20260323
The GIRR Risk Factor Structure at a Glance
| Risk Measure | Dimensions | Structure |
| Delta | 2 | Yield curve per currency × 10 prescribed tenors, plus a flat inflation factor and a flat cross-currency basis factor per currency. |
| Vega | 2 | Option maturity (5 tenors) × underlying residual maturity (5 tenors), per currency. |
| Curvature | 1 | Constructed risk-free curve per currency only — no term structure decomposition. No curvature charge for inflation or cross-currency basis. |
Looking Ahead
With the full risk factor structure now in place, Part B turns to the practical machinery: how currencies are grouped into buckets, the risk weights assigned to each tenor, and the correlation parameters used to aggregate GIRR sensitivities within and across those buckets.
Frequently Asked Questions
What are the ten GIRR tenors?
0.25, 0.5, 1, 2, 3, 5, 10, 15, 20 and 30 years — the fixed tenor structure to which delta GIRR risk factors are assigned for every currency.
Does inflation risk get a curvature capital charge?
No. Inflation risk and cross-currency basis risk are both captured only under delta GIRR — neither generates a curvature risk capital requirement.
What happens if a bank can’t split a bond yield into its risk-free and credit spread components?
The sensitivity to that yield gets allocated to both the GIRR and CSR risk classes, using the standard’s risk factor and sensitivity definitions for each — preventing a bank from using an imprecise proxy to under-capture credit spread risk.
For previous article: